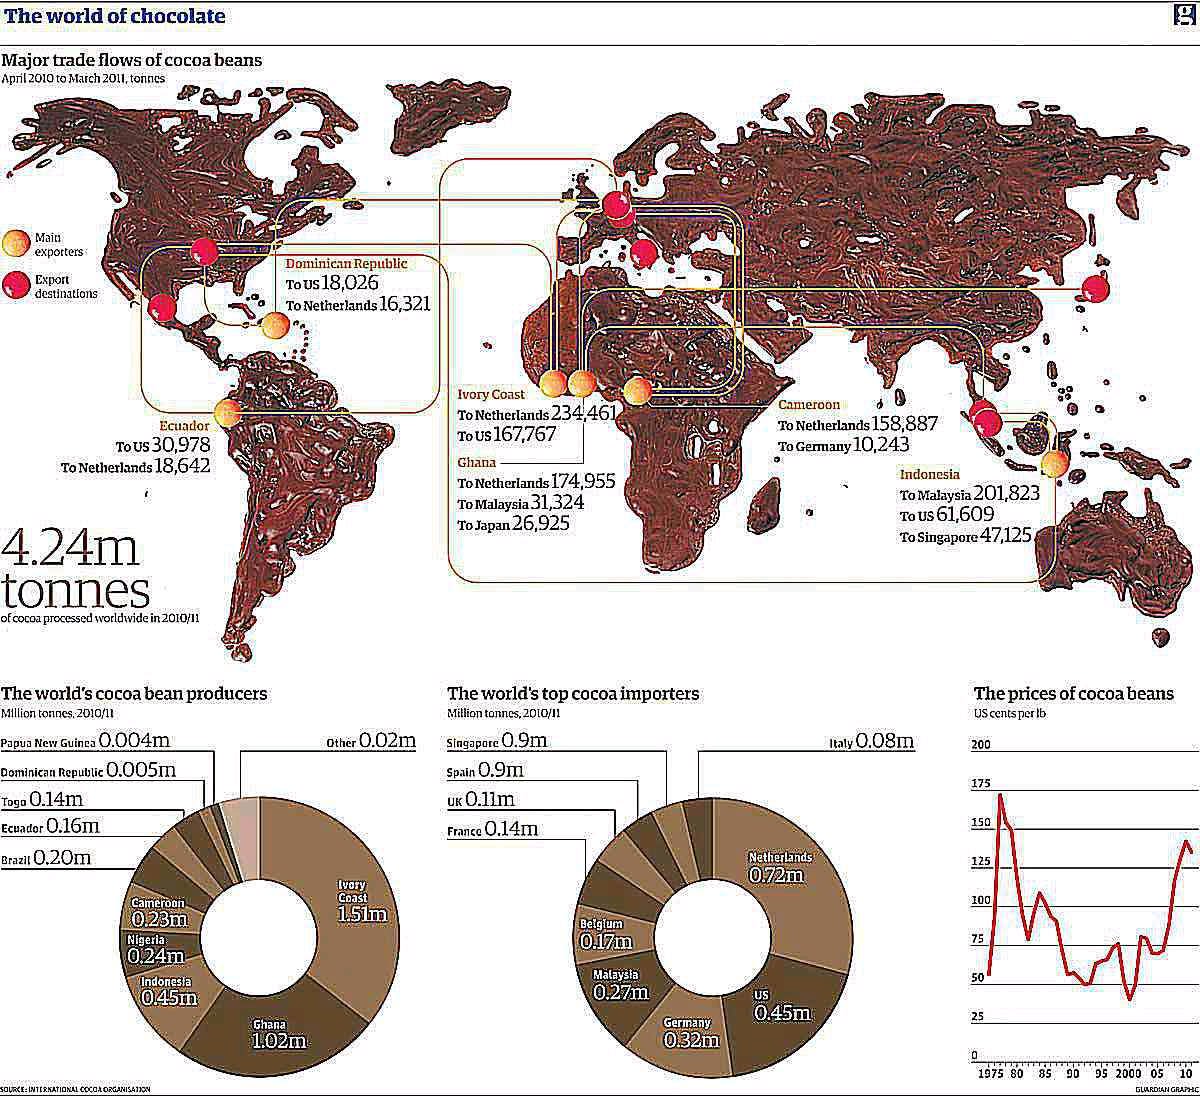
Cocoa market conditions have shifted notably in recent days, with major producing countries making decisions that can affect supply flows and pricing dynamics. Reporting indicates Côte d’Ivoire is adjusting how it defines the mid-crop season and the fixed farmgate price paid to producers, partly to address unsold stocks and competitiveness. At the same time, Ghana’s cocoa financing pressures have been highlighted, with liquidity risks affecting buyers and payments in the sector. These upstream changes do not always translate quickly into supermarket pricing, because manufacturers may be working through contracts, inventory, and hedging positions. A perception gap can emerge where commodity prices move, but consumer prices respond slowly or unevenly. This question focuses on expectations rather than opinions of “right” or “wrong” policy, which helps reduce bias and captures forward-looking sentiment.